Rejection City

Five everyday rejections. Fix them.

0 of 5 fixed

A toy-brick city seen from above: a café, a council office, an office tower, a bank and a cash machine, all grey, around a zebra crossing.

All brands are fictional. Scene images made with AI; screens, flows and reasoning designed by Elmira Hummatzade.

All fixes

Every screen before and after, with the reason behind each change. Pick a place.

1. Café: payment declined

Rejection

She pays for a flat white and a croissant, and the screen says “Transaction failed. Code 05.” Code 05 is the generic “do not honour” decline, a catch-all that doesn’t carry the bank’s real reason.

Corner Cup Your order Flat white + croissant £6.40 Transaction failed. Code 05. Your bank declined this payment Please try again. You haven’t been charged. Your order is saved, so you can pay another way. Think this is a mistake? Your bank made this decision, so contact them to check your card. OKTapping OK clears your order. Try another cardPay with phone walletWhy might my bank decline this?
Before. Her card payment fails with only an error code.
Corner Cup Your order Flat white + croissant £6.40 Transaction failed. Code 05. Your bank declined this payment Please try again. You haven’t been charged. Your order is saved, so you can pay another way. Think this is a mistake? Your bank made this decision, so contact them to check your card. OKTapping OK clears your order. Try another cardPay with phone walletWhy might my bank decline this?
After. Same moment, redesigned: what happened, what it means, what to do.

Three fixes, and why

  1. “Code 05” , fixed as “Your bank declined this payment.”

    Understand

    Why. Say who decided and what happened. The café can’t know the bank’s reason, so it shouldn’t pretend to.

  2. Nothing about money , fixed as Adds “You haven’t been charged.”

    Understand

    Why. Answer the first worry before it’s asked.

  3. “OK” empties the order , fixed as “Try another card” and “Pay with phone wallet”, the order kept, and who to contact if it's a mistake.

    Act

    Why. A specific next step instead of a dead end.
2. Cash machine: pin locked

Rejection

She types the wrong PIN too many times and the screen says “Account locked. Please contact your bank.” The bank has made a security decision, so this is a rejection too.

Northgate Bank Account locked. Your PIN is locked after 3 wrong triesYour account and your money are safe. Only PIN use is paused. No way to unlock it here Unlock it now in your banking app. Scan to open. Please contact your bank. Your card has been returned Call 0800 000 0000, free, 8am to 8pm Or visit any branch
Before. The machine keeps her card's PIN locked and says nothing useful.
Northgate Bank Account locked. Your PIN is locked after 3 wrong triesYour account and your money are safe. Only PIN use is paused. No way to unlock it here Unlock it now in your banking app. Scan to open. Please contact your bank. Your card has been returned Call 0800 000 0000, free, 8am to 8pm Or visit any branch
After. Same moment, redesigned: what's blocked, how to unlock it, who to call.

Three fixes, and why

  1. “Account locked” , fixed as “Your PIN is locked after 3 wrong tries. Your account and money are safe.”

    Understand

    Why. Say exactly what’s blocked and what isn’t.

  2. No way to unlock , fixed as “Unlock it now in your banking app” with a QR code.

    Act

    Why. A way back she can take herself, straight away.

  3. “Contact your bank” , fixed as That the card was returned, a free phone number with opening hours, or any branch.

    Contest

    Why. A real route to a person, not just an instruction.

3. Bank: loan refused

Rejection

She applies for a £5,000 personal loan, and the advisor’s tablet shows one line: “Your application was unsuccessful.”

Northgate Bank Personal loan · £5,000 over 3 years Your application was unsuccessful. We couldn't approve your loan this timeWe know this isn't the answer you hoped for. This is mainly because of information on your credit file. No mention of which credit agency was checked We checked your file with Checkwell Credit Reference Contact details and how to get your free report Close What you can do next 1.Check your free credit report2.Ask us to review this decision3.Wait before applying again: each application leaves a search on your file Free, independent help: MoneyHelper (moneyhelper.org.uk) Check my credit report Ask for a review
Before. Her £5,000 loan is refused with one line and a Close button.
Northgate Bank Personal loan · £5,000 over 3 years Your application was unsuccessful. We couldn't approve your loan this timeWe know this isn't the answer you hoped for. This is mainly because of information on your credit file. No mention of which credit agency was checked We checked your file with Checkwell Credit Reference Contact details and how to get your free report Close What you can do next 1.Check your free credit report2.Ask us to review this decision3.Wait before applying again: each application leaves a search on your file Free, independent help: MoneyHelper (moneyhelper.org.uk) Check my credit report Ask for a review
After. Same moment, redesigned: the main reason, who holds her file, what to do next.

Three fixes, and why

  1. No reason given , fixed as “We couldn't approve your loan this time”, a kind line, and the main reason: her credit file.

    Understand

    Why. The main reason, which the Ombudsman expected lenders to give.

  2. No credit agency named , fixed as Names the credit reference agency checked, with contact details.

    Understand

    Why. Consumer Credit Act s.157. Only 7 of 16 lenders give this in full.

  3. Only a Close button , fixed as Three next steps, two clear buttons, and free help from MoneyHelper.

    Contest and act

    Why. A review button in the same screen avoids the letter or branch visit some lenders ask for.

4. Council office: form error

Error

She submits a resident parking permit form on a kiosk, and it wipes everything she typed because of one mistake in the postcode. Nobody has refused her anything. The system just handled invalid input badly.

Riverside Council Apply for a resident parking permit There were errors in your submission. There is a problemEnter a full UK postcode Full name Address Full nameElmira Hummatzade Address12 Riverside Road, London Postcode SW1A 1A Invalid input Postcode Enter a full UK postcode, like SW1A 1AA SW1A 1A Car registrationAB12 CDE Continue
Before. Her parking permit form comes back empty, with a vague error.
Riverside Council Apply for a resident parking permit There were errors in your submission. There is a problemEnter a full UK postcode Full name Address Full nameElmira Hummatzade Address12 Riverside Road, London Postcode SW1A 1A Invalid input Postcode Enter a full UK postcode, like SW1A 1AA SW1A 1A Car registrationAB12 CDE Continue
After. Same moment, redesigned: her answers kept, each problem named and linked.

Three fixes, and why

  1. Fields wiped , fixed as Everything she typed is kept.

    Error fix

    Why. Don’t make people start again for one mistake (Neusesser and Sunwall, 2023).

  2. Vague banner , fixed as An error summary that lists each problem and links to its field.

    Error fix

    Why. The GOV.UK Design System error summary pattern.

  3. “Invalid input” , fixed as "Enter a full UK postcode, like SW1A 1AA" above the field.

    Error fix

    Why. Say what to do, with an example, without blaming the person.

5. Office tower: job rejection

Rejection

In the lobby where she interviewed, an automated rejection arrives 47 days later from a no-reply address. This isn’t a financial decision, but the same three aims still apply.

Inbox no-reply Received 47 days after your interview Sam Patel, Recruiter at Brightline Replies welcome Your application: Product Designer Thank you for your time. We've decided not to move forward with your application. Please do not reply to this email. We'd like to keep you in mind for similar roles.Questions about this decision? Reply to this email and Sam will get back to you. See related roles
Before. 47 days after her interview, a no-reply email closes the door.
Inbox no-reply Received 47 days after your interview Sam Patel, Recruiter at Brightline Replies welcome Your application: Product Designer Thank you for your time. We've decided not to move forward with your application. Please do not reply to this email. We'd like to keep you in mind for similar roles.Questions about this decision? Reply to this email and Sam will get back to you. See related roles
After. Same moment, redesigned: a real person, a short reason, a door left open.

Three fixes, and why

  1. “no-reply” sender , fixed as Sent by a named recruiter, replies welcome.

    Contest and tone

    Why. A person she can answer.

  2. No feedback , fixed as One or two honest lines on why.

    Understand

    Why. A short reason gives her something to work on.

  3. A dead end , fixed as “We'd like to keep you in mind for similar roles”, a link, and an invite to reply with questions.

    Act

    Why. An alternative, the dimension only 7 of 16 lenders offered.

Behind the city

A design research project in two parts: a study of how UK banks and lenders tell people no, and Rejection City, where you fix the screens yourself.

The bank scene from Rejection City: my toy-brick character smiles at a tablet across the desk from a bank advisor.

Overview

I studied how UK lenders tell people their application has been declined: 20 lenders' public pages, 12 Financial Ombudsman Service decisions and the UK rules that apply. The research tells me what a rejection message needs. Rejection City is where I tried to show it.

Why rejections

Product teams spend most of their time on the path where everything goes right. The moment a product says no gets far less attention. I designed rejection screens in a regulated financial product before, and that work showed me how much a single screen has to carry when the answer is no.

What I found

Reasons are the weakest part. Next steps are the strongest. My reading is that the room to improve sits less in the decision and more in how it is told.

Research Snapshots

How many of 16 UK lenders' public pages clearly include each part of a rejection message, collected on 8 November 2026.

  • A specific next step 14 of 16 lenders
  • A route to a person or a challenge 10 of 16 lenders
  • A respectful tone 9 of 16 lenders
  • Credit reference agency details 7 of 16 lenders
  • An alternative 7 of 16 lenders
  • The applicant's own reason 1 of 16 lenders

What stood out

None blame the applicant. In the Ombudsman decisions I read, money was awarded only for communication failures, never for the decision itself.

What a good rejection needs

An explanation of a decision should help a person understand it, contest it and change what they do next. I use those three aims to group what the research, the rules and the Ombudsman decisions point to.

  • Understand

    The main reason in plain words. Where a lender can't share its criteria, what would need to change. For credit, which credit reference agency was used and how to contact it.

    Why it matters: Explanations help most after a bad outcome, and wrong or generic reasons led to Ombudsman awards.

  • Contest

    An easy route to a person or a review, in the same channel the person used.

    Why it matters: The Consumer Duty warns against unreasonable barriers, and wrong appeal advice led to an Ombudsman award.

  • Act

    A specific next step, said the same way on every page, and a pointer to free, independent help.

    Why it matters: Contradictory advice on when to reapply confuses people.

Across all three

A respectful tone that doesn't blame. These recommendations come from documents. I haven't tested them with people who have been declined.

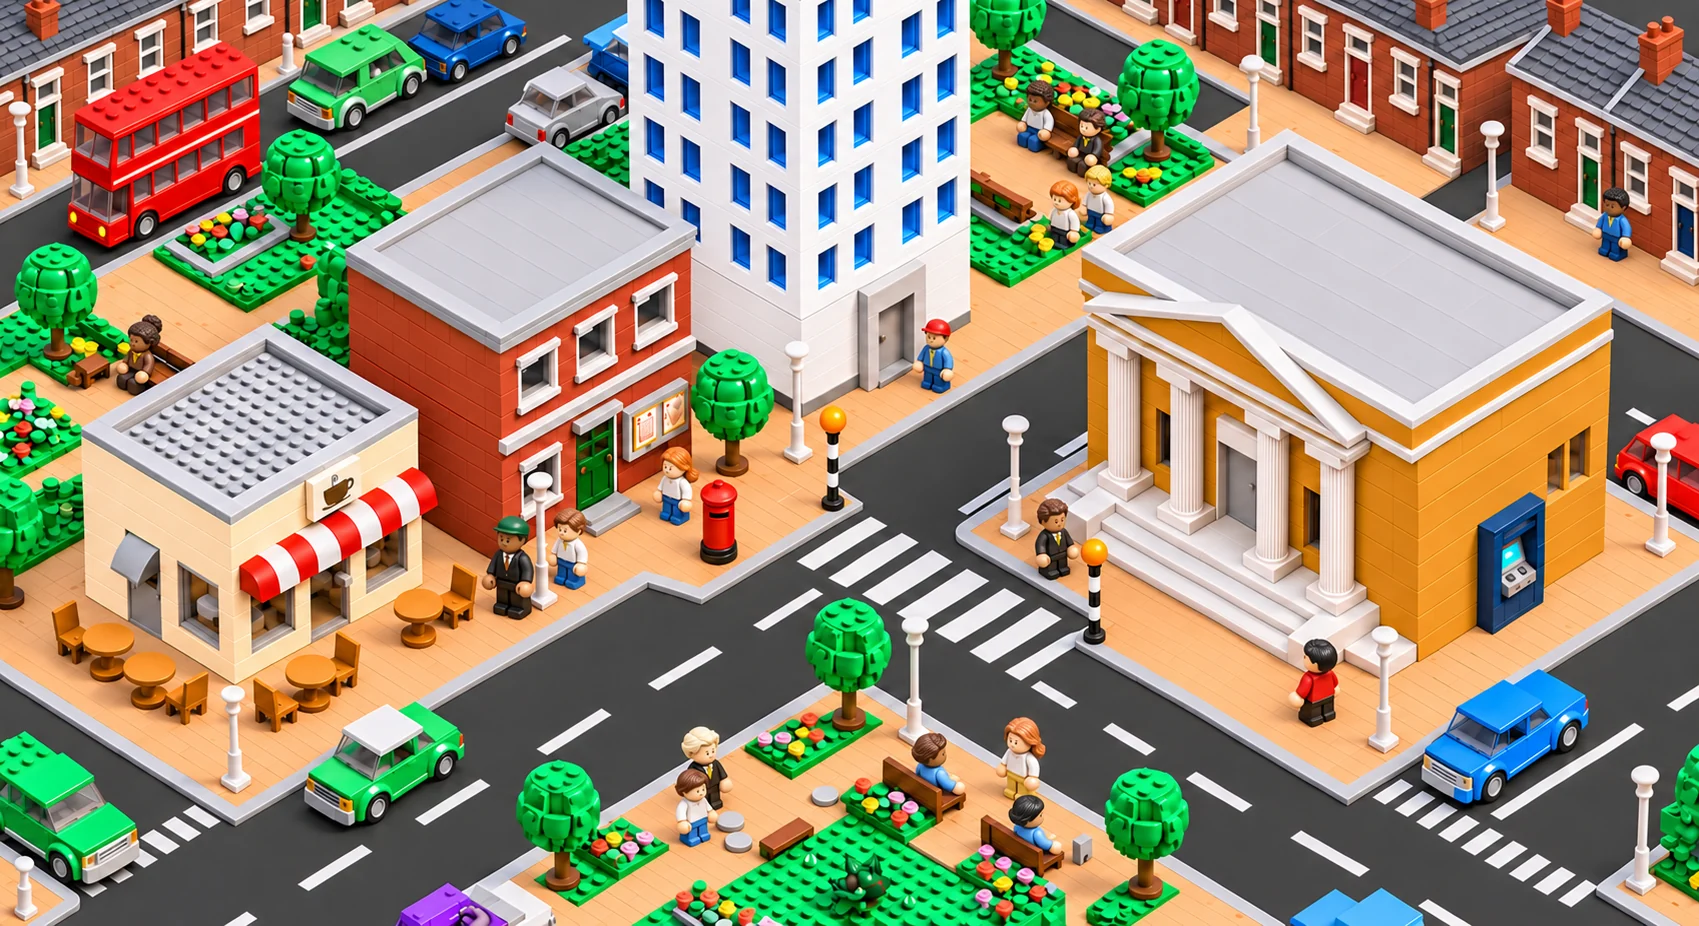
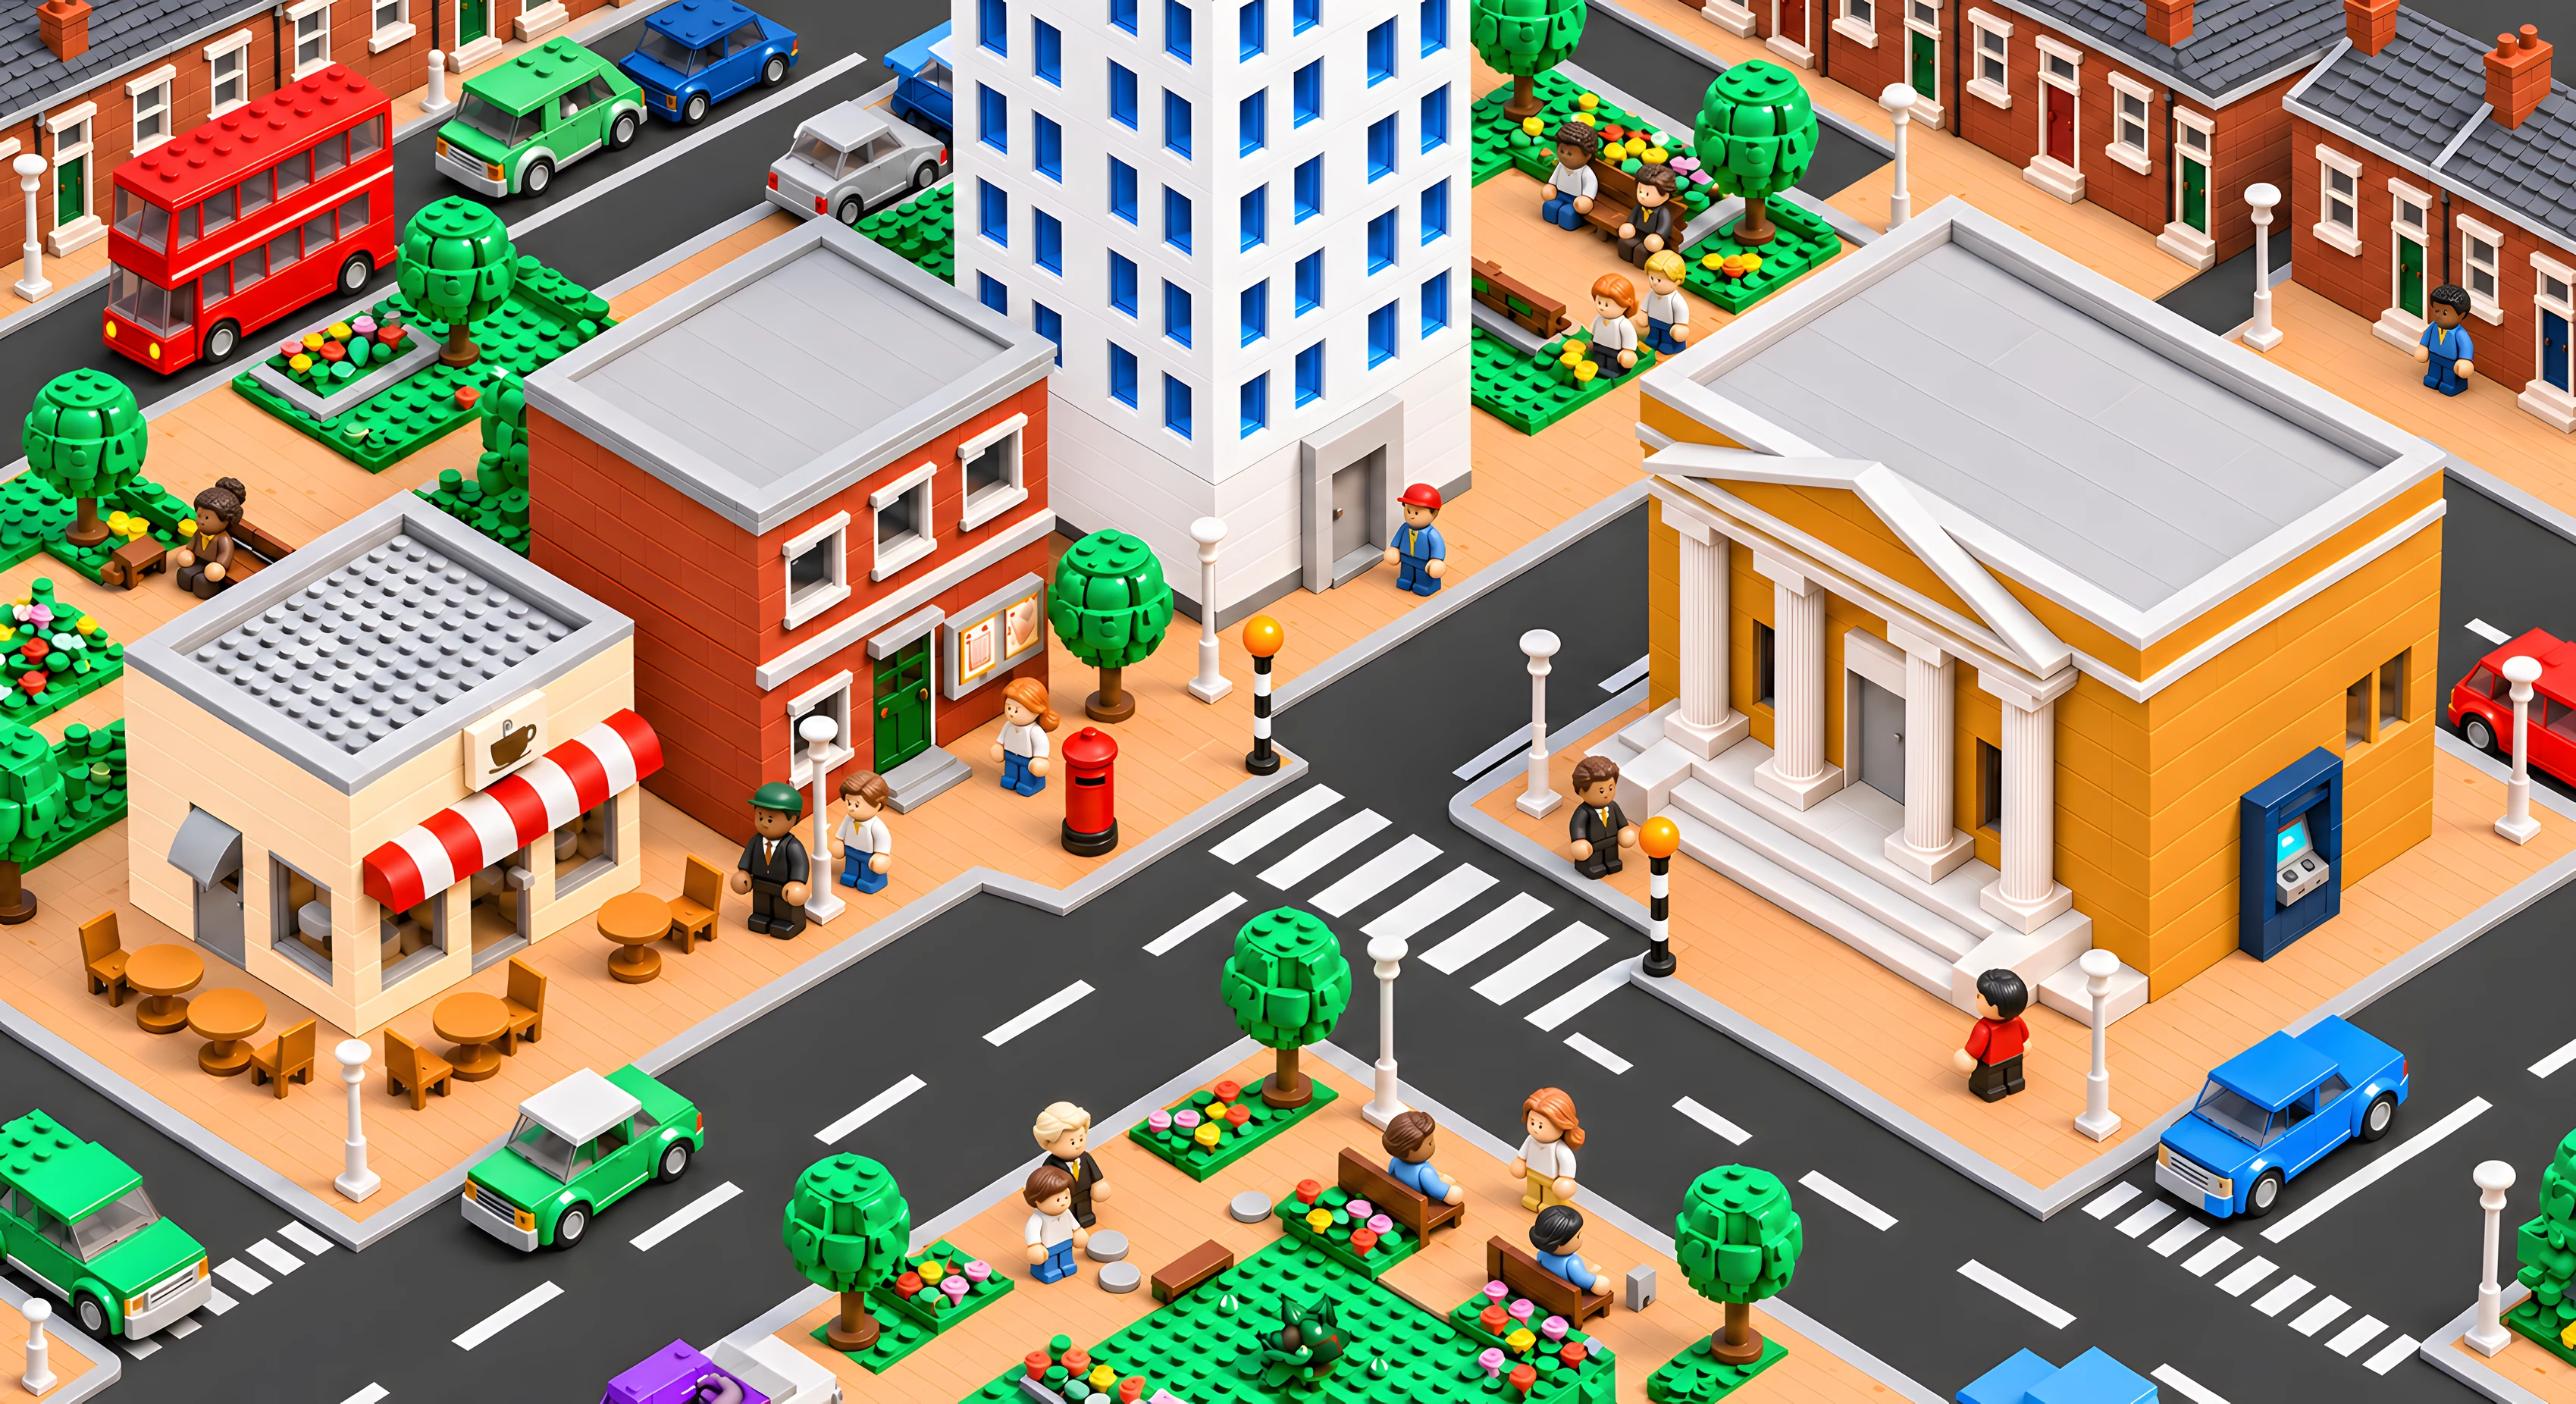
Rejection City in colour: a toy-brick UK street with a café, a council office, an office tower, a bank and a cash machine around a zebra crossing.

What I researched

How UK digital financial services communicate rejections, and what a rejection message needs in order to be understood and accepted. I used document analysis, so the study is built on public documents, not interviews or user tests. I scored each lender on six things a message can include, as Present, Partial or Absent, with a quote as evidence.

How the city uses it

The bank scene comes straight from the research. The café and the cash machine are financial rejections the audit didn't cover. The office uses the same three aims outside finance. The council scene is the contrast on purpose: it's an error, not a rejection.

A rejection is not an error

A rejection is a decision: an application refused, a payment declined. It has to be understood, then accepted, challenged or worked around. An error is a technical fault that can usually be fixed by trying again. Most published guidance covers errors. Very little covers rejections.

How I made it

I used AI throughout, and I want to be clear about which parts were mine.

Me AI
Research Chose the topic, the questions, the method and the six dimensions. Checked the scores. Helped collect lender pages and Ombudsman decisions and did the first coding against my guide.
Idea and scope Chose the city, the five places, the grey to colour mechanic and the three fixes per screen. Suggested starting ideas.
Images Art-directed every image: my character, the UK street, the camera, what each frame shows. Rejected many versions. ChatGPT generated the images from prompts written to my rules.
Screens and copy Chose the flaws and the fixes, approved every line, set the visual direction. Claude drafted copy and built the click flows in Figma.
Build Tested it on my own computer. Claude Code wrote the code from my build brief.

The hardest part

Keeping the images consistent. What worked was strict rules and one change per edit, always starting with 'Keep everything exactly the same. Only...'.

Sources

The research, rules and guidance behind the city and its fixes.

  • Alaybek, B. et al. (2022) 'All's well that ends (and peaks) well? A meta-analysis of the peak-end rule and duration neglect', Organizational Behavior and Human Decision Processes, 170.
  • Bowen, G.A. (2009) 'Document analysis as a qualitative research method', Qualitative Research Journal, 9(2), pp. 27 to 40.
  • Colquitt, J.A. (2001) 'On the dimensionality of organizational justice', Journal of Applied Psychology, 86(3), pp. 386 to 400.
  • Consumer Credit Act 1974, s.157.
  • Data (Use and Access) Act 2025, s.80.
  • Financial Conduct Authority (2022) FG22/5 Final non-Handbook guidance for firms on the Consumer Duty.
  • Financial Conduct Authority, PRIN 2A.6: consumer support outcome.
  • Financial Ombudsman Service, published Ombudsman decisions.
  • GOV.UK Design System, Error summary.
  • Information Commissioner's Office and The Alan Turing Institute (2020) Explaining decisions made with AI.
  • Lending Standards Board (2025) LSB's Standards of Lending Practice for personal customers to be retired in March 2025.
  • Neusesser, T. and Sunwall, E. (2023) Error-message guidelines. Nielsen Norman Group.
  • Shaw, Wild and Colquitt (2003).
  • Wachter, Mittelstadt and Russell (2018).

Limits and what comes next

What this study can and can't tell you, and what I'd test next.

  • Help pages aren't decline screens. The study shows what lenders publish, not the message someone actually sees.
  • Ombudsman cases are complaints, so they show the declines that went badly.
  • Counts are based on 16 of 20 lenders. It's a snapshot from 8 November 2026, and pages change.
  • Nothing here has been tested with people. Next: usability testing of rejection messages built on understand, contest and act.